

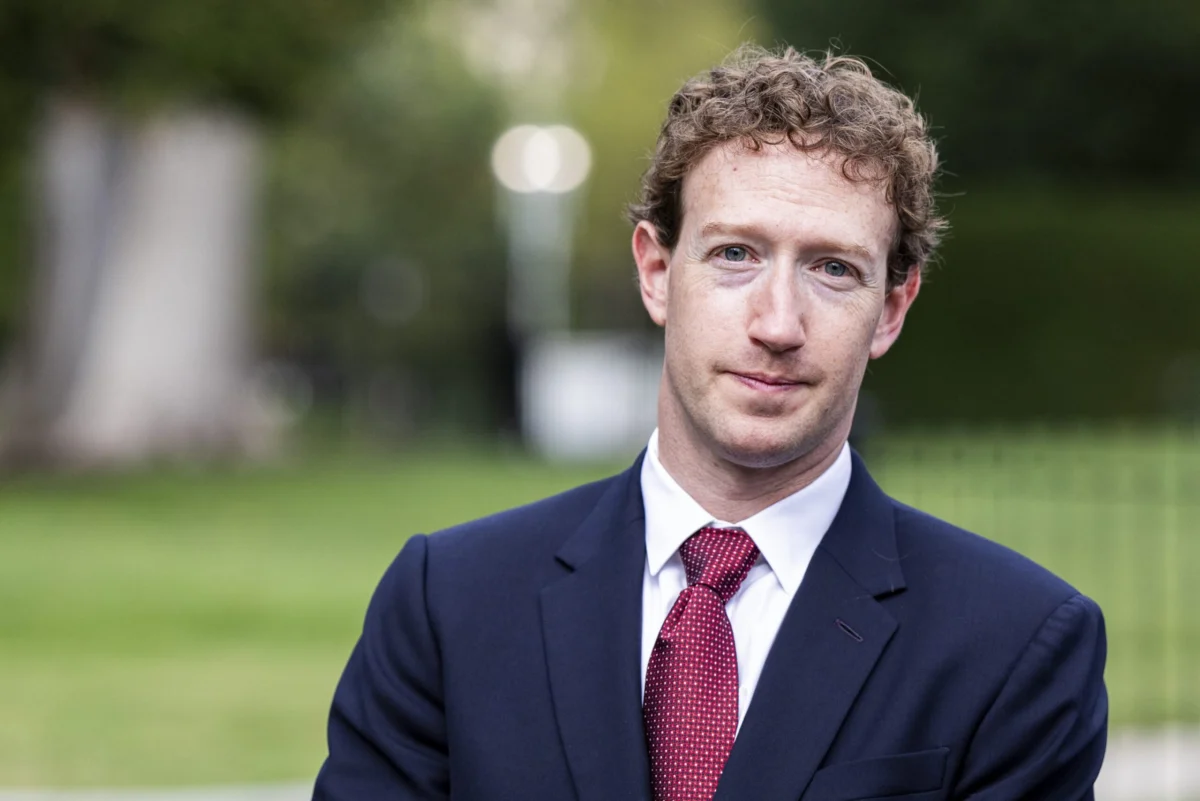
In a move that underscores the singular influence of Mark Zuckerberg over the company he founded in 2004, Meta Platforms has unveiled a sweeping capital structure reorganization. Following the release of its third-quarter 2026 earnings, the tech giant announced the issuance of a new class of non-voting stock—Class C shares—designed to preserve Zuckerberg’s ironclad control while providing the company with the fiscal flexibility required to navigate an increasingly capital-intensive era of artificial intelligence.
The decision, which follows months of high-stakes negotiations between Zuckerberg and a special committee of the board, represents more than just a financial maneuver. It is a masterclass in corporate governance engineering, balancing the founder’s desire for autonomy with the company’s urgent need for liquidity to fuel its massive AI buildout.
The Mechanics of the New Class C Shares
Meta’s capital structure has historically relied on a dual-class system. Class A shares, which trade on the Nasdaq, carry one vote per share. Class B shares, held predominantly by Zuckerberg, carry 10 votes per share, granting him approximately 60.6% of the company’s total voting power despite owning only 13.4% of the equity.
The new Class C shares are structured as a one-for-one stock dividend distributed to all current shareholders. These shares carry no voting rights. By introducing this non-voting currency, Meta gains a powerful tool: it can now issue equity to employees, pursue strategic acquisitions, or raise external capital without diluting Zuckerberg’s voting majority.
Perhaps most crucially for the CEO, the Class C shares allow him to generate personal liquidity—to fund the Chan Zuckerberg Initiative or satisfy potential tax obligations—without triggering the conversion of his super-voting Class B shares into Class A shares, a standard "poison pill" mechanism that has long served as a tether on founder control.
A Chronology of Contention
The path to this structural shift was anything but smooth. The internal dialogue between Zuckerberg and the board’s special committee—which included DoorDash CEO Tony Xu, Ambassador Robert Kimmitt, and former Microsoft executive Charles Songhurst—was marked by friction, brinkmanship, and the genuine threat of mass resignation from the committee members.
Summer 2026: The Tax Looming Over Palo Alto
The tension centered on California’s proposed Proposition 40, a wealth tax initiative set for the November 3, 2026, ballot. Given Zuckerberg’s net worth—pegged by the Bloomberg Billionaires Index at roughly $246 billion—the tax posed a multibillion-dollar liability.
In July, Zuckerberg initiated conversations with lead independent director Robert Kimmitt, expressing concern that selling Class B shares to cover such a tax bill would erode his voting stake, potentially pushing it below the 50% threshold. The committee, meanwhile, sought to introduce "sunset provisions"—clauses that would automatically convert Class B shares into standard equity upon the founder’s death, departure, or the sale of a significant portion of his holdings.
The Threat of Exodus
By late July, the negotiations hit a stalemate. Zuckerberg remained steadfast in his refusal to accept sunset provisions. On July 30, the conversation took a dramatic turn when Zuckerberg informed the committee that he was "considering establishing residence outside of California" to avoid the impact of Proposition 40.
For the board, this was not merely a personal relocation; it was a potential strategic disruption. The committee, concerned with Meta’s need to keep its leadership close to its primary AI research labs, scrambled to find a middle ground. However, when Zuckerberg’s legal team subsequently requested a "moonshot" performance pay package—similar to those granted to Elon Musk at Tesla or SpaceX—the committee balked.
The August Brinkmanship
August saw a flurry of proposals and rejections. On August 4, Zuckerberg proposed a 20-for-1 dividend of Class C shares. The committee deemed this "excessive." As the month wore on, the committee members grew increasingly frustrated, going as far as to discuss the possibility of resigning en masse if their concerns regarding the rights of Class A shareholders were not addressed.
The September Resolution
The turning point arrived at a board dinner on September 9. Zuckerberg informed directors that he intended to list his Palo Alto estate for sale within days. The committee, sensing the potential for a total breakdown in governance, moved quickly.
A compromise was struck on September 14. Zuckerberg agreed to drop his request for a performance-based pay package, maintain his $1 salary, and commit to remaining in California (or wherever Meta is headquartered) for the next eight years. In return, the committee agreed to the Class C dividend structure. The board sealed the deal on October 19, with the Chan Zuckerberg entities—which control 56% of the vote—providing their blessing the following day.
Supporting Data: The AI Spending Crunch
The urgency of this restructuring is laid bare in Meta’s recent financial disclosures. The company is currently engaged in a massive, capital-intensive pivot toward artificial intelligence that has strained its balance sheet.
- Third Quarter 2026 Performance: Meta reported revenue of $64.6 billion, a 26% increase year-over-year.
- Capital Expenditures (CapEx): Expenditures reached $34.9 billion in the third quarter alone. The company has revised its 2026 full-year CapEx guidance upward, now expecting to spend between $135 billion and $140 billion.
- Free Cash Flow: Once a juggernaut of cash generation, Meta’s free cash flow dipped to negative $2.1 billion, a stark contrast to the $10.6 billion reported in the same quarter the previous year.
- The Buyback Drain: Meta previously relied on stock buybacks to offset the dilution of equity compensation. In 2025, the company repurchased $26.3 billion in Class A shares. However, that practice has ceased for four consecutive quarters as the company pivots its cash toward AI infrastructure.
Official Responses and Strategic Rationale
During the earnings call on Wednesday, Meta CFO Susan Li defended the decision as a necessary evolution of the company’s capital framework. "We thought it was prudent to establish the appropriate capital structure framework to ensure that we have access to a diverse pool of funding sources," Li stated.
The rationale is clear: by creating a non-voting currency, Meta can continue to compete for top-tier AI talent through equity grants and potentially raise capital in debt or equity markets without the founder needing to sacrifice his influence. The company effectively separates the economic interest of shareholders from the control interest of the founder, a configuration that has become increasingly common in the modern tech landscape.
Implications: A New Era for Meta Governance
The successful implementation of this share class structure signals several long-term implications for the company and its shareholders:
- Founder Perpetuity: By securing his voting control against the threat of wealth taxes and dilution, Zuckerberg has effectively insulated his leadership from the vagaries of political tax policy and market-driven dilution for the foreseeable future.
- The "Staple" Requirement: The agreement includes a unique "stapling" provision. While Zuckerberg can sell 20% of his new Class C shares immediately, the remaining 80% can only be sold if he simultaneously sells or converts an equivalent number of his Class B voting shares. This ensures that his long-term exit or reduction in influence remains tethered to his voting power.
- Governance Precedent: The committee’s struggle highlights the challenges boards face when dealing with "founder-dictators." While the committee successfully blocked a lucrative pay package and secured a commitment for the CEO to stay in California, the ultimate resolution was a victory for the founder’s desire to maintain centralized control.
- Investor Outlook: Shareholders will now be watching to see how the new Class C stock performs and whether the massive investment in AI infrastructure, funded by this new flexibility, will deliver the long-term growth the market expects. With annual returns tied to the distribution of future Class C dividends, shareholders have a tangible incentive to hope for consistent, high-level growth.
As Meta enters the final months of 2026, the company stands at a crossroads. By formalizing this new capital structure, Mark Zuckerberg has secured the financial tools necessary to wage an aggressive war for AI dominance, while simultaneously ensuring that the company’s vision remains anchored to his own. Whether this consolidation of power will lead to sustained innovation or eventual governance stagnation remains the defining question for Meta’s second act.
