

In the world of Financial Independence, Retire Early (FIRE), there is a persistent, almost ideological, tendency to treat Social Security as a non-entity. For those planning to exit the workforce in their 30s or 40s, the program often feels like a distant, unreliable abstraction—a "fuzzy concept" that won’t kick in until the golden years. However, as the FIRE movement matures, a growing cohort of early retirees is discovering that Social Security is not just a safety net for the elderly; it is a powerful, inflation-adjusted financial instrument that can significantly alter one’s retirement math today.
The Paradigm Shift: From "Useless" to "Strategic Asset"
For decades, the narrative has been clear: rely on your own savings, ignore the government, and build a "stash" that sustains you entirely independently. While this remains a sound philosophy for risk mitigation, it ignores the reality of the Net Present Value (NPV) of future cash flows.
Whether you are a thirty-something software engineer or a fifty-five-year-old professional facing a mid-career pivot, Social Security represents a future stream of income. By calculating the NPV—the current value of a future stream of payments, discounted by an assumed rate of return—retirees can integrate this benefit into their current balance sheets.

If you are 30, the NPV of your Social Security is effectively near zero because the compounding power of your own investments far outweighs the distant payout. But for those in their 50s and 60s, that "fuzzy concept" begins to solidify into a massive, tangible asset. Treating it as a component of your net worth doesn’t mean you must rely on it; it means you can accurately assess your "safety margin," potentially allowing you to retire sooner or spend more confidently.
A Chronology of Calculation: The NPV Approach
The confusion surrounding Social Security often stems from the myriad of conflicting opinions on when to claim. Should you take it at 62? Wait until your Full Retirement Age (FRA)? Or hold out until 70 to maximize the monthly payout?
To demystify this, we must look at the time value of money. Let’s examine the "Shane Survivor" scenario—a 55-year-old looking to exit the workforce.

The 55-Year-Old’s Dilemma
Shane has a modest nest egg and is debating whether to grind for another decade. Traditional advice dictates working until 67 or 70 to maximize the benefit. However, when we apply the NPV formula, a counterintuitive truth emerges: waiting for higher benefits is not always the superior financial move.
If Shane claims benefits at 62 and invests that money—assuming a conservative 6% annual return after inflation—the compounding effect creates a "snowball." By the time a 67-year-old retiree begins their higher monthly payments, the early claimant who invested their benefits has already built a substantial buffer. The math reveals that for many, the "gap" in benefits is never fully bridged by the higher payout, because the early claimant has had five extra years of capital appreciation.
Supporting Data: The Power of the "Stash"
The math becomes clearer when we look at the mechanics of the payout. The Social Security Administration (SSA) calculates your benefit based on the average of your 35 highest-earning years. For those who retire early, the "zero years" (years with no income) are factored into the average, which sounds penalizing. However, the system is progressive; it replaces a higher percentage of income for low-to-moderate earners than for high earners.

The 10-Year vs. 35-Year Contributor
Consider two individuals:
- The Marathoner: Works 35 years at $100k/year.
- The Sprinter: Works 10 years at $100k/year, then retires.
While the Sprinter only contributes roughly 28% of what the Marathoner contributes, their eventual Social Security benefit is often nearly 45% of the Marathoner’s. This "slacker incentive" is a structural quirk that favors those who prioritize life over career longevity. Furthermore, most "early" retirees find that through side hustles, consulting, or small business ventures, they continue to contribute well beyond their initial ten-year sprint, further bolstering their benefit average without the soul-crushing 9-to-5 grind.
Official Perspectives and Government Sustainability
A recurring question among the FIRE community is: "What if the program is cut?"

It is a valid concern. The Social Security Trust Fund faces solvency challenges that will require legislative action in the coming decade. However, political reality suggests that the program is untouchable for current and near-future retirees. Because the demographic of voters is skewing older, any drastic reduction in benefits would be political suicide.
The most likely outcome of any reform will be means-testing. If you have been diligent enough to accumulate a multi-million dollar portfolio, you might see your benefits reduced. However, this is a "good problem to have." If you are wealthy enough to be means-tested, your reliance on Social Security was minimal to begin with. Viewing Social Security as a "bonus" rather than a "requirement" insulates you from this risk.
Implications for Your Retirement Strategy
Integrating Social Security into your retirement planning requires a shift in perspective. You are not "waiting" for the government; you are "accounting" for a future annuity.

The Three-Step Action Plan:
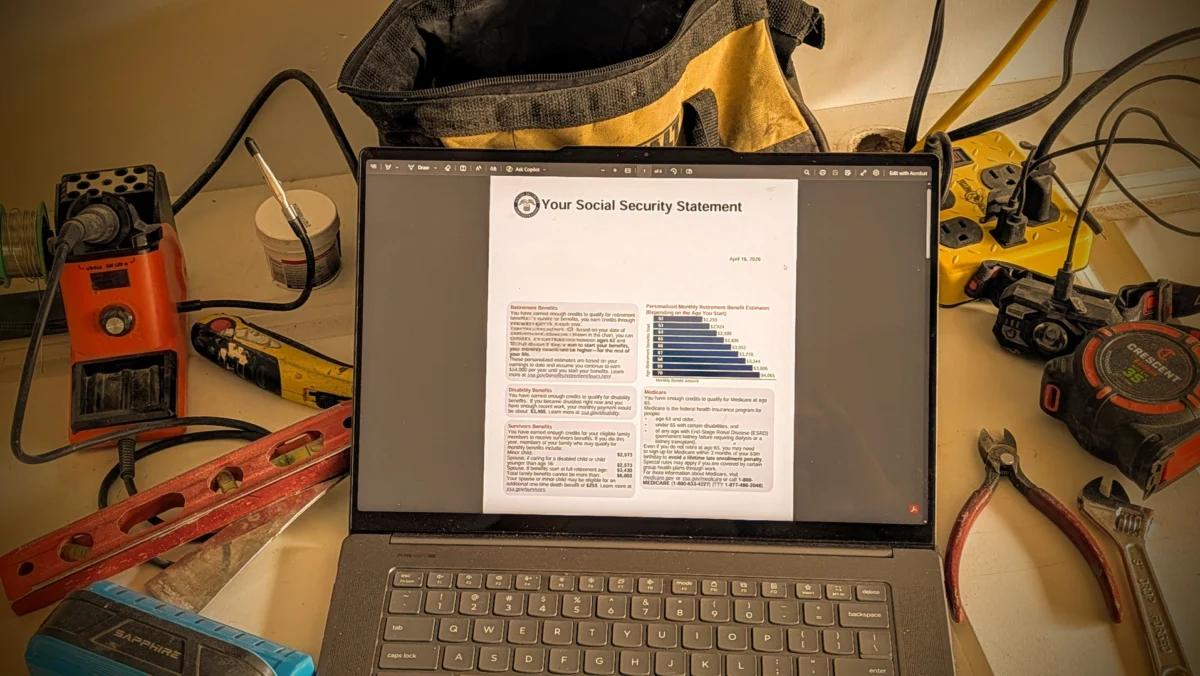
- Audit Your Status: Log into SSA.gov. This is the single most important piece of "homework" for any retiree. It provides your personalized earnings history and benefit estimates.
- Calculate the NPV: Don’t be intimidated by the formula. Use online NPV calculators or leverage AI tools like Claude, Gemini, or ChatGPT. Input your age, your expected monthly benefit, and your target retirement age. The resulting number is the "shadow asset" you can add to your net worth.
- Adjust Your "Safe Withdrawal Rate": If you have $1 million in investments and an NPV of $300k in Social Security, you are effectively a $1.3 million household. This allows you to potentially increase your annual spending or reduce your current savings rate, accelerating your transition to freedom.
The Psychological Dimension of Wealth
Beyond the spreadsheets and the NPV formulas, there is a deeper issue: the role of worry in our financial lives. Many people who have reached "financial independence" still suffer from a scarcity mindset. They hoard cash, they work longer than necessary, and they fear the market.
By formalizing the value of Social Security, we are not just doing math; we are buying peace of mind. Recognizing that you have a floor—a government-backed, inflation-adjusted stream of income—should fundamentally change how you view your investment risk. It allows you to shift from a mindset of "survival" to one of "thriving."
Conclusion: The New Frontier of FIRE
The early retirement movement is evolving. We have moved past the era of simply "cutting costs" and "investing in index funds." We are now entering an era of sophisticated financial management where tools like Social Security are integrated into the holistic picture.

Whether you are 30 or 55, the strategy remains the same: stop ignoring the program. Treat it as a potential pillar of your retirement, calculate its value, and use that information to reclaim your most precious asset: your time. If you can retire three years earlier because you finally accounted for that future check, you haven’t just optimized a spreadsheet—you have bought back three years of your life.
And in the end, isn’t that what the FIRE movement was always about?
