

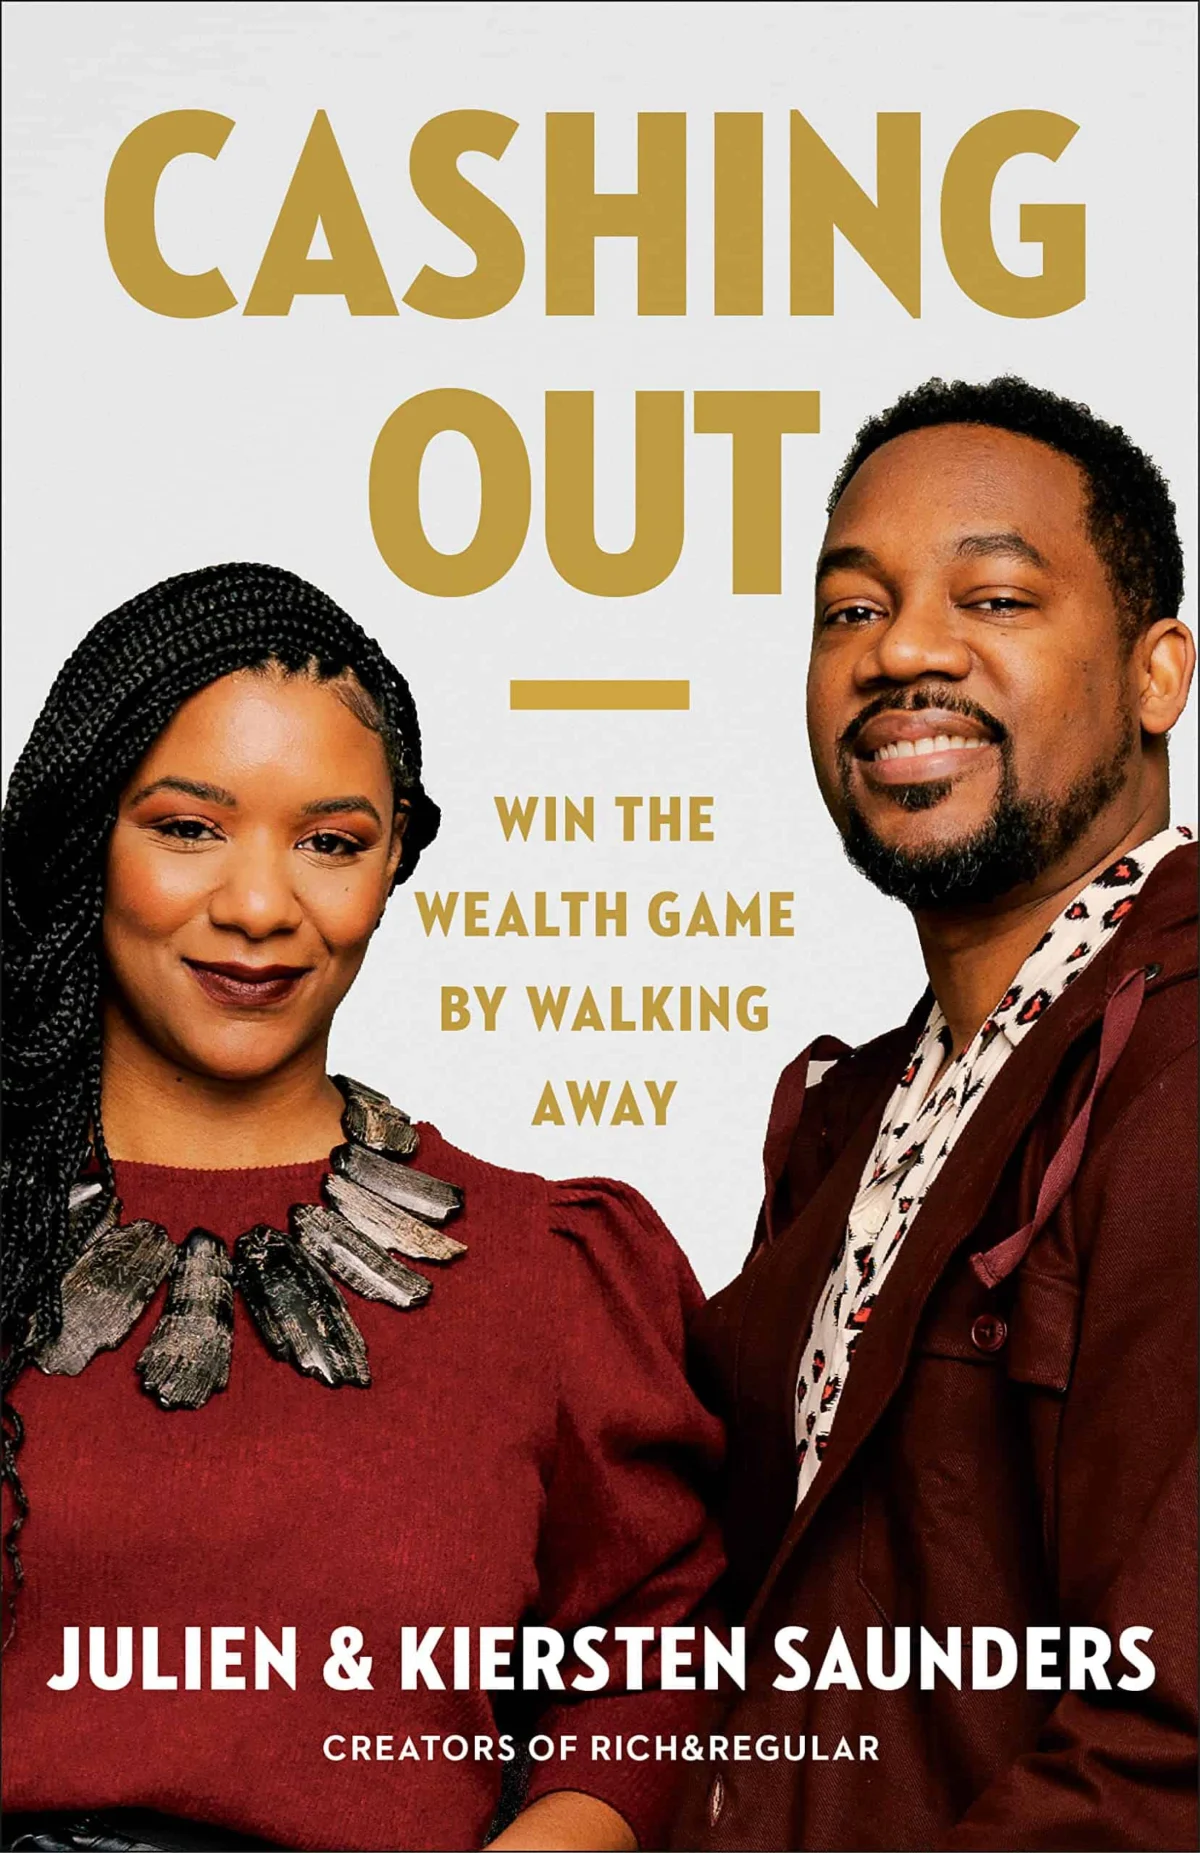
For many couples, money is not merely a tool for survival or a means to an end; it is a profound, often volatile, emotional language. When financial discourse breaks down, the resulting friction can destabilize even the most solid foundations. In their latest book, Cashing Out: Win the Wealth Game by Walking Away, financial experts and "power couple" Julien and Kiersten Saunders—the voices behind the influential platform rich & Regular—argue that the discord couples feel regarding money is rarely about the bank account. Instead, they suggest it is a failure of "emotional attunement."
Drawing on the principles of Dr. Sue Johnson’s Emotionally Focused Therapy (EFT), the Saunders suggest that financial arguments are essentially a "dance." When a partner makes a move—whether it is a purchase, a savings goal, or a disclosure of debt—the other responds in a set pattern. If the rhythm is off, the dance collapses. To build long-term wealth, couples must learn not just to manage numbers, but to synchronize their movements.
The Dance of Discord: Understanding Financial Attunement
Dr. Sue Johnson, a preeminent clinical psychologist, posits that the "dance" is the problem, not the individuals involved. By reframing conflict as a pattern of interaction rather than a character flaw, couples can move away from blame.
The Saunders define "emotional attunement" as the ability to recognize your partner’s emotional rhythm. If conflict is the dance, then emotions are the music. A major source of dysfunction in financial communication is the "silent disco" phenomenon: two partners attempting to move through life while listening to entirely different soundtracks. One might be dancing to the high-tempo urgency of future-proofing, while the other is swaying to the rhythm of present-day enjoyment. Unless both parties can acknowledge the other’s soundtrack, they will continue to step on each other’s toes.
Chronology of Conflict: How Money Issues Evolve
The journey of financial friction typically follows a predictable trajectory, often beginning with unspoken assumptions and culminating in hardened defense mechanisms.
- The Phase of Avoidance: Early in a relationship, money is often treated as a taboo subject. This creates a vacuum where partners operate in silos, leading to "silent disco" behavior.
- The Trigger Event: A specific incident—a large unexpected purchase, a missed bill, or the discovery of debt—shatters the illusion of financial alignment.
- The Labeling Phase: To cope with the stress of the trigger, partners reach for easy heuristics. This is when the "Saver vs. Spender" narrative is born.
- The Cycle of Escalation: This stage is characterized by either name-calling (about spending habits), nagging (about saving goals), or blaming (about debt).
- The Breaking Point or Breakthrough: The couple either enters a cycle of perpetual resentment or adopts new communicative tools—such as the "tell me more" approach—to realign their rhythm.
Supporting Data: Debunking the "Saver vs. Spender" Paradigm
A central pillar of the Saunders’ philosophy is the dismantling of the "Saver vs. Spender" dichotomy. This binary framing is not only reductive but often serves as a weapon for moral superiority.
In the Cashing Out framework, these labels are exposed as a misunderstanding of time horizons. "Spenders" are simply people prioritizing utility and satisfaction in the present. "Savers" are individuals prioritizing utility and satisfaction in the future.
The Time Horizon Shift
- The Paradigm Swap: Moving from a "good vs. bad" judgment to a "now vs. later" perspective.
- The Emotional Objective: Every financial transaction, whether it is a $5 latte or a $50,000 investment, is an attempt to achieve a specific feeling—security, pleasure, or spontaneity. By identifying the underlying emotional goal, couples can bypass the moral judgment of the purchase and instead discuss the efficacy of the strategy.
When couples realize that their goal is not to be a "saver" or a "spender," but rather to achieve a state of harmony where both present and future needs are met, the tension dissipates.
The Three Pillars of Financial Friction
The Saunders identify three primary arenas where the dance typically fails:
1. Name-Calling: The Spending Conflict
When one partner critiques the other’s spending, it often masks a deeper fear. If partner A sees a pile of Amazon boxes and feels "irresponsible," they are actually expressing anxiety about their future security. If partner B sees a strict budget and feels "controlled," they are expressing a need for autonomy.
2. Nagging: The Saving Conflict
Nagging is identified as "conversational quicksand." By turning saving into a daily chore—akin to taking out the trash—the requester inadvertently signals that their primary issue is with the partner’s character, not the household balance sheet. The authors suggest that instead of policing, couples should pivot to "future-casting." By discussing the excitement of future goals (e.g., a vacation or a home renovation), the conversation becomes an exercise in shared optimism rather than a lecture on willpower.
3. Blaming: The Debt Conflict
Debt is perhaps the most emotionally charged topic. It often brings shame to the borrower and resentment to the partner who feels forced to carry the load. The Saunders emphasize that true attunement requires the shedding of "hero/villain" narratives. Whether a couple chooses to combine finances to tackle debt or keep them separate to maintain individual agency, the success of the strategy depends on the underlying communication.
Official Perspectives and Expert Implications
The implications for couples looking to achieve financial independence are clear: Financial health is a subset of relational health.
In their analysis, the Saunders highlight the importance of the "Tell Me More" technique. This phrase acts as a conversational circuit breaker. When a partner feels the urge to judge or criticize, the invitation to "tell me more" forces a pause, allowing the other person to articulate their perspective without the immediate threat of condemnation.
However, the authors provide a critical caveat: timing is everything. Using this phrase during a moment of high emotional volatility—when a partner is crying or feeling under attack—can feel like a weaponized interrogation rather than an act of curiosity. In moments of extreme stress, the authors advise prioritizing the "dance floor" over the "dance." In other words, prioritize the health of the relationship over the immediate resolution of the financial problem.
Conclusion: Toward a Synchronized Future
The transition from a fractured financial relationship to a unified one is not an overnight process. It requires the deliberate practice of empathy and a commitment to viewing one’s partner as a teammate rather than an adversary.
As the summer of books at Get Rich Slowly concludes, the lessons from Cashing Out serve as a reminder that the path to wealth is rarely a straight line. It is a collaborative, ongoing performance. By trading judgment for curiosity, and by aligning our emotional music with that of our partners, we can transform the chaotic, often painful dance of money into a graceful, coordinated, and ultimately rewarding experience.
For those looking to deepen their financial intimacy, the path is simple, if not easy: Stop labeling, start listening, and remember that you are both dancing to the same song—you just need to make sure you can hear it.
